“So many requirements and I still got disapproved!”
That’s the complaint. But here’s what’s actually underneath it. Three questions nobody ever states out loud: how much can I borrow, at what rate, and on what terms. Those are the only questions that matter when it comes to business loan eligibility in the Philippines. The
checklist was never going to answer them.
Age 25–70. A year in operation. A permit. A registered business. If you ticked every box, here’s what you’ve earned: the right to be considered. The entry ticket into any SME business loan in the Philippines. Not the decision.
Want to know what lenders actually measure?
The 3 Factors Behind Business Loan Eligibility in the Philippines
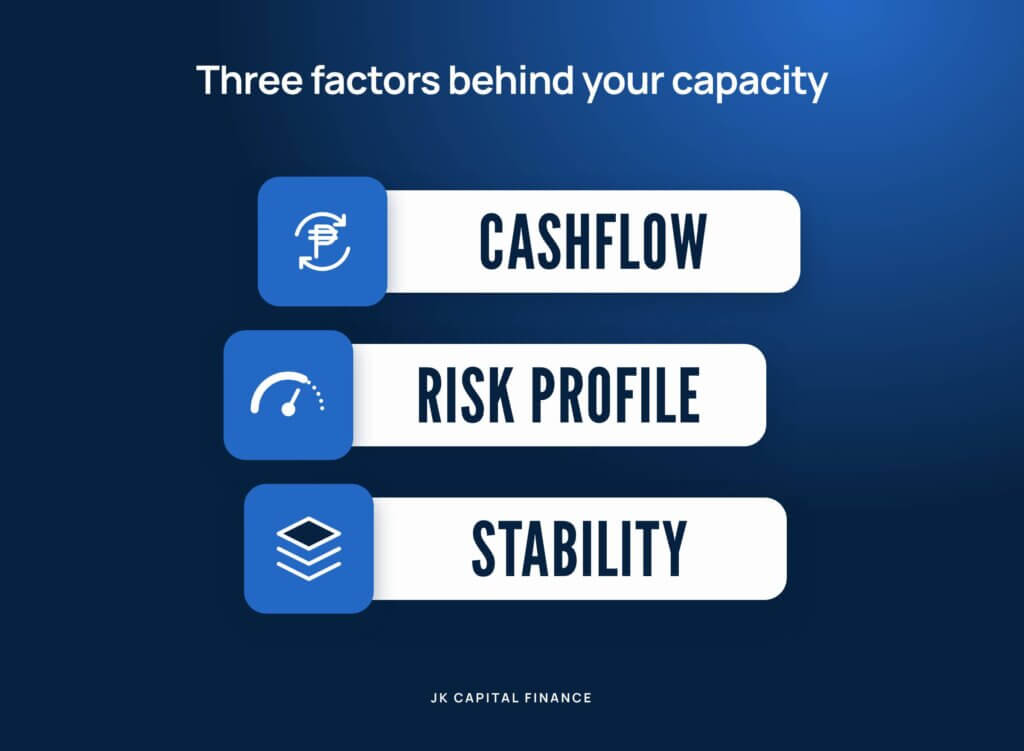
The decision comes from three factors, read together, never in isolation.
Cashflow. The money is actually moving through your business.
Risk profile. How much of your borrowing room is already spoken for.
Stability. The depth behind your numbers — years, assets, a track record.
For a better grasp of what these three mean, try asking yourself these questions:
- “Does my cash coming in comfortably outpace what goes out — even in an average month, not just a good one?”
- “Have I paid past obligations on time, or is there a bounced check or missed payment sitting somewhere in my history?”
- “Is my business built to still be standing in three years, or is this year’s number the only proof I’ve got?”
Add the three answers together and you get one number. Not a pass or a fail. That number is your borrowing capacity for extra credit.
And here’s the part that changes how you should think about all three: a weakness in one can be offset by another. Thin cashflow, carried by years of stability. A tighter risk profile, carried by a steady track record. A newer business, carried by strong early cashflow. None of the three needs to be perfect. They just need to be read together, honestly.
This is exactly why we walk owners through it before they apply. JK Capital isn’t just processing your file. We’re teaching the framework behind it, so you’re never guessing at what’s actually being measured. Our loan consultants sit with you, walk through your cashflow, your risk profile, your stability, and tell you plainly where you stand, before you commit to anything. Financial literacy isn’t a side benefit here. That’s the point.
Which JK Capital Financing Fits Your Business?
Once you know where you stand on cashflow, risk, and stability, the next question is which kind of financing actually fits. Three places most owners start:
- Working Capital Loan: Funding for day-to-day operations such as inventory, payroll, and supplier payments. Built for businesses with steady cashflow that need breathing room between cycles.
Business Loan: A term loan for bigger moves like expansion, new equipment, or a new branch. Best when your stability and track record can support a longer repayment schedule.
Receivables Financing: Turn unpaid invoices into cash now instead of waiting 30, 60, or 90 days for clients to pay. If your own cash flow is thin, your customers’ payment record can help carry the application.
Not sure which one fits? That’s exactly what our loan experts are for.
So don’t walk in guessing about how much you can borrow. Read yourself first — cashflow, risk, stability, together. Bring a complete file, and you’ll get a pre-qualification answer in 24 hours, before you commit to anything.
₱300K–₱50M. Pre-qualified in 24 hours.
Pre-qualification within 24 hours of document submission. Approval in 7 banking days from complete documents, subject to credit evaluation.
Ready to find out where you stand?
JK CAPITAL: Financing Your Next Breakthrough
We fund from P300,000 to P50 million, released in 5-7 days, so you can move on opportunities without losing them to delay. Over 10,000 SMEs funded. More than a decade of figuring out what works for businesses like yours. Beyond capital, we’re your partner in the breakthrough.